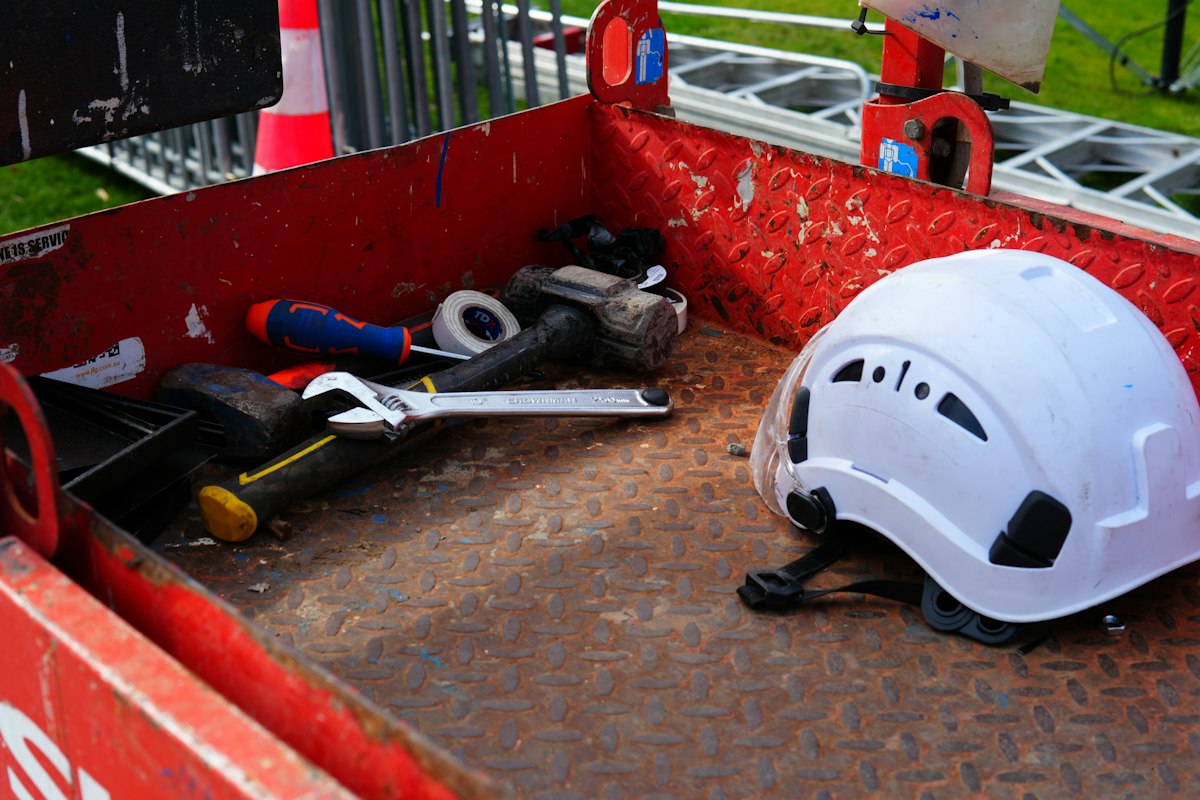
Construction in the Pikes Peak region has not slowed down. The Pikes Peak Regional Building Department reported roughly $3.7 billion in total construction value for 2025, up 8% from 2024, with permits for new commercial projects up 31% and more than 2,700 apartment units permitted. More job sites means more skid steers, trailers, compressors, and trucks full of tools sitting out overnight in Briargate, Banning Lewis Ranch, and along the Powers corridor. It also means more targets.
Thieves have noticed. In 2025, six men were sentenced to between 10 and 20 years in prison for a theft ring that hit 39 construction sites across the Front Range and walked off with more than $1.1 million in tools and equipment, according to CBS Colorado. Most of those sites were north of us, but Monument was on the list, and the playbook travels. If you run a crew in El Paso County, contractor equipment insurance is the coverage that decides whether a theft is an annoying week or a real hit to your business.
Here is the part that surprises people. Your general liability policy will not pay for stolen equipment, and your commercial property policy probably won't either once that equipment leaves your yard.
Contractor equipment insurance is a type of inland marine coverage. Colorado has no coastline, so the name throws people off. It is a holdover from the days when insurers covered cargo moving by ship and river, and over time it grew to mean coverage for any property that moves. Today, inland marine protects your tools and equipment wherever they happen to be: on a job site in Fountain, in the back of your truck on I-25, or staged at a project in Falcon.
Depending on how the policy is written, it can cover tools and heavy equipment you own, lease, or borrow, both on the job and in storage. Covered losses typically include theft, vandalism, fire, and weather events like hail and lightning. You may also hear it called a tools and equipment policy or an equipment floater. Same idea, different label.
Think of it like a seatbelt for your gear. Your truck has auto insurance. Your shop has property insurance. But the stuff that rides between the two, the stuff that actually makes you money, needs its own protection that goes where it goes.
General liability pays for damage you cause to other people and their property. It was never built to pay for your own equipment. If you want the full picture on what GL does handle, we broke it down in our post on general liability insurance in Colorado Springs.
Commercial property is the one most contractors assume will step in. The catch is that a standard commercial property policy is written around the address listed on the policy. Once your excavator or compressor leaves that location, coverage typically drops off or shrinks to a small off-premises extension that won't come close to replacing a trailer full of gear. The fix is to schedule that equipment under an inland marine contractors equipment form, where the items are specifically listed and theft is covered.
Builder's risk gets mixed into this conversation a lot, so a quick note. Builder's risk protects the structure going up on the site. The tools and machines used to build it need their own coverage. Our post on builder's risk insurance in Colorado explains how that piece fits. Plenty of contractors need both.
Knowing the limits matters as much as knowing the coverage. Many policies have conditions around tools stolen from an unlocked vehicle, and that catches contractors off guard after a truck break-in. Read that section of your policy before you need it, and lock up every night.
Normal wear and tear isn't covered either. This is insurance for sudden, unexpected loss, so routine replacement of worn-out tools stays on you. And most policies carry per-item or per-occurrence limits. If you own a single piece of equipment worth $40,000, schedule it individually on the policy instead of lumping it into a blanket limit that might come up short at claim time.
Hail gets the headlines here, and it should. Anyone who has worked an open site on the Front Range in June knows how fast a storm can roll off the mountains and pound equipment sitting in the open. A covered perils list that includes weather matters. But the less obvious Colorado issue is distance. Equipment gets moved between the Springs and mountain jobs in Woodland Park, Divide, and Teller County, and it often sits on rural sites without fencing or lighting. Every one of those details is something an underwriter asks about, and every one is a place where a poorly set up policy can leave you short.
Then there's rented equipment. Plenty of local contractors rent a lift or a trencher for a week and assume the rental company's damage waiver or their GL policy has them covered. Usually neither does the job well. If you're responsible for a rented machine while it's on your site, make sure your policy is set up to cover equipment you don't own. A rented machine that disappears is still your bill to the rental company unless the coverage was there.
As a local agency, we have a deep understanding of Colorado and its unique areas and their specific insurance requirements. That includes knowing how carriers look at a yard in Falcon or a job site in Monument, and what they will ask about security before they quote.
Start with a walk through your yard and your trucks with a notepad. Write down every piece of equipment, its make, model, serial number, and what it would cost to replace today. Use today's price, not what you paid three years ago. Replacement cost is where most contractors come up short, because equipment prices have climbed and the number in your head is probably old.
Next, sort the list into three groups: big items you want scheduled one by one, smaller tools you can cover under a blanket limit, and rented or borrowed items you only have part of the year. Each group can be handled differently, and how you split them changes your premium.
Then talk about the deductible. Theft is the most likely claim on this kind of policy, and some carriers have a separate theft deductible or special conditions for equipment left unattended or stored outside. Ask your agent to show you exactly where the policy addresses unattended equipment and trailers, because that is where claims get argued.
On cost, premiums swing a lot based on what you own, where it's kept, your claims history, and the deductible you choose. A small crew's hand tool package prices very differently than a fleet of heavy equipment, so the only useful number is a quote built from your actual list. You can see everything else we write for contractors on our business insurance page.
Q: Does my commercial property insurance cover equipment on a job site?
Usually not in any meaningful amount. A standard commercial property policy is written around the location listed on the policy. Once your tools and equipment leave that address, whether they are on a job site, in your truck, or in transit, coverage typically drops off or is limited to a small extension. Contractor equipment coverage is built to fill that gap.
Q: Is inland marine insurance the same thing as tools and equipment coverage?
In most cases, yes. Carriers call it inland marine, contractors equipment, a tools and equipment policy, or an equipment floater. The idea is the same across all of them: coverage for property that moves with you. What changes from carrier to carrier is what the form includes and excludes, which is why the actual policy language matters.
Q: Does contractor equipment insurance cover equipment I rent?
It can, but only if the policy is set up for it. Many carriers can include leased, rented, or borrowed equipment while it is in your care. If you rent lifts, trenchers, or other machines for specific jobs, ask your agent to confirm rented equipment is on your policy before you sign the rental agreement.
You work hard for the gear in your trailer. If your current policy doesn't specifically list it, there's a good chance it won't respond when something walks off a site in the middle of the night. Pull out your policies this week and look for the words "inland marine" or "contractors equipment." If you don't see them, you probably have a gap.
Give us a call or start a quote online, and we'll look at what you have and tell you exactly where you stand.