Every summer, the construction boom hits Colorado Springs hard. Roofing crews are working six days a week, concrete subs are backed up for weeks, and framing contractors are pulling permits faster than inspectors can process them. And every summer, I get the same question from guys who have been in the trades for years: "Tommy, do I actually need workers' comp? I'm just me."
It is the most common workers' compensation insurance question Colorado Springs contractors get wrong, and the consequences of getting it wrong range from an awkward conversation to a business-ending liability. Here's what the law actually says, how it applies to subcontractors, and what you should do if you're not sure where you stand.
Workers' compensation is mandatory in Colorado for any business with employees. That's the simple version. The moment you put someone on payroll, whether full-time, part-time, or seasonal, you are required to carry coverage. No grace period. The Colorado Division of Workers' Compensation has the authority to fine you $500 per day for every day you operate without it, and if one of your employees gets hurt while you're uninsured, you are on the hook for the full claim out of pocket plus a 25% penalty on top of their benefits.
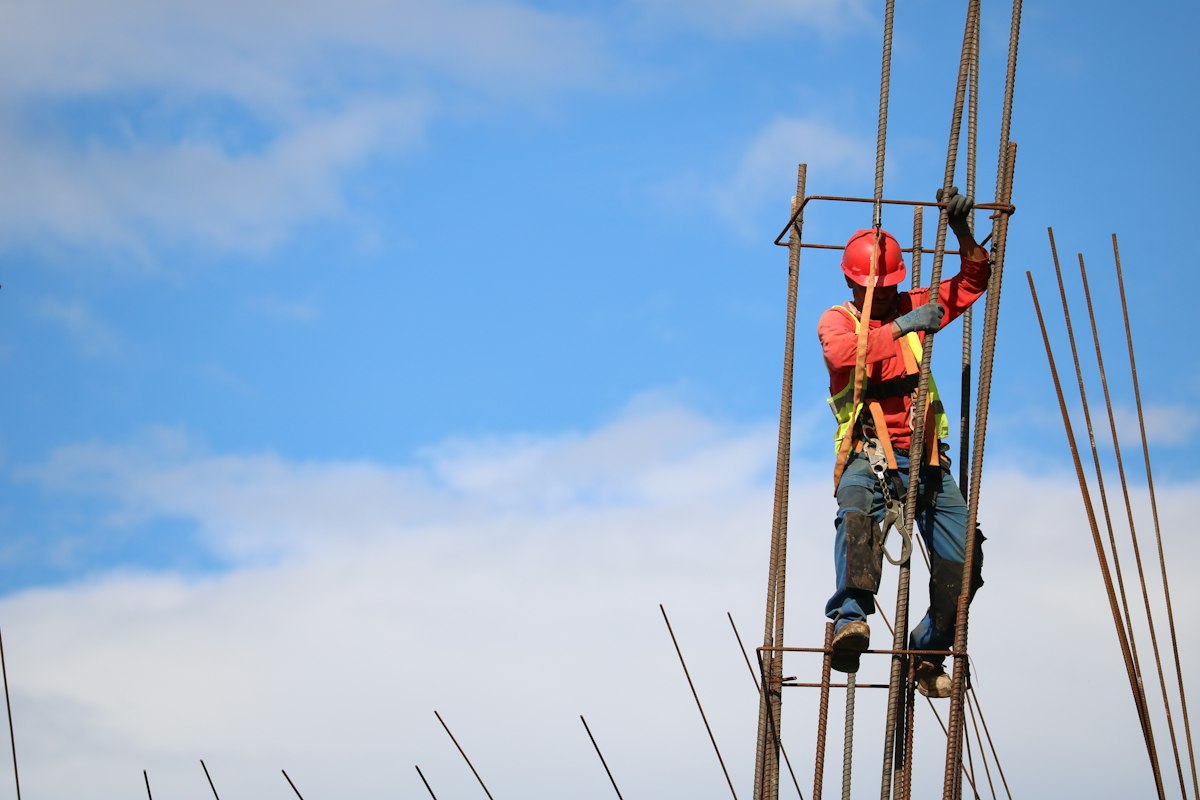
For small contractors in El Paso County, that is not a theoretical risk. Worksites are inherently hazardous, and a single fall, a ladder accident, or a machinery injury can generate six-figure medical bills fast. Workers' comp exists because those situations happen to experienced people on ordinary job sites.
The good news: Colorado has seen workers' compensation loss costs drop for twelve consecutive years. The Colorado Division of Insurance approved a 6.9% reduction in average loss costs for 2026, which matters if you're a small contractor watching your overhead. But affordable doesn't mean optional. Knowing what you're required to carry is the first step.
Here's where it gets complicated, and where most sole proprietors either relax too early or panic unnecessarily.
If you are a sole proprietor with no employees, Colorado does not require you to carry workers' compensation insurance for yourself. The state does not classify sole proprietors as employees, so you are technically exempt. If you get hurt on a job site, that's a conversation for your health insurance and disability coverage, not a workers' comp policy.
But there is a construction-specific carve-out worth knowing. If your business is in the construction industry and you are a sole proprietor, you must either formally carry workers' comp coverage for yourself or reject that coverage in writing. You do not get to simply ignore the question. Construction gets treated differently than most other industries in Colorado, so if you are a sole proprietor swinging a hammer in El Paso County, it's worth confirming which side of that line you are actually on.
The second thing that trips people up is growth. The day you bring on a helper, even temporarily, even for one summer project, the exemption disappears. You go from zero compliance obligation to full coverage required, immediately. A lot of small operators get caught here because they think of "employees" as meaning full-time, W-2, year-round people. Colorado does not make that distinction. If someone is working for you and does not meet the state's specific definition of an independent contractor, they are an employee under the law, and you need coverage before they start.
If you work as a subcontractor, or if you hire subcontractors to handle part of your scope, this section matters a lot.
Colorado law says that if a general contractor brings in a subcontractor who does not carry workers' compensation insurance, the GC can be held liable for any work-related injuries that sub's workers suffer on the job. The risk does not stop at the subcontractor's business. It moves up the chain to whoever hired them. That is why most general contractors in Colorado Springs and across El Paso County require proof of coverage before any sub sets foot on a project.
If you are a subcontractor trying to land work with larger GCs in the area, not having workers' comp is often a non-starter regardless of what the law technically requires. The GC's insurance team will ask for a certificate of insurance that includes workers' comp, and usually general liability coverage alongside it. If you can't provide one, you're losing the bid to someone who can. Voluntary coverage is essentially a market requirement even when it's not a legal mandate.
On the flip side, if you are a GC hiring subs, do not rely on a signed contract alone to prove independent contractor status. The Colorado Division of Workers' Compensation looks at the actual working relationship, not just the paperwork. If a sub's workers are using your equipment, working your hours, and following your direct supervision, there's a real chance they would be classified as your employees in a dispute. That misclassification exposure is significant and worth taking seriously before it becomes a claim.
What you'll pay depends on several factors, and the range is wide enough that a general number without context doesn't help you much.
The biggest driver is payroll, since premiums are calculated as a rate per $100 of covered payroll. Your classification code moves the number significantly as well. Roofing carries a higher rate than drywall finishing, for example, because the injury risk is higher. Your claims history also plays a role. A clean record with no prior claims will put you in a better position at renewal than a history of frequent incidents.
For a small Colorado Springs contractor with one or two employees, workers' comp premiums often fall somewhere in the range of $3,000 to $8,000 annually, depending on the trade and total payroll. That's a wide spread, and your specific situation could land anywhere in it. The only way to know your actual number is to run a quote with the details of your operation.
Colorado employers can purchase coverage through Pinnacol Assurance, the state's competitive fund, or through any licensed private carrier. Working with an independent agent who has access to multiple carriers means you're not just getting one option. You're getting a comparison of what the market looks like for your specific trade and risk profile, which often makes a meaningful difference in what you pay. As a local agency, we have a deep understanding of Colorado and its unique areas and their specific insurance requirements, and workers' comp is one of the lines where that matters. You can see the rest of what we handle for contractors on our business insurance page.
Q: Do I need workers' comp if I'm a sole proprietor in Colorado?
Generally, no. If you have no employees, you are exempt from the mandate. However, if you are in the construction industry, you must either carry coverage for yourself or formally reject it in writing. And the moment you hire anyone, you need coverage immediately, regardless of how the work is structured.
Q: What happens if I hire a subcontractor who doesn't have workers' comp?
If that sub or their workers are injured on your job site, you could be held responsible for their claim under Colorado law. Always collect a certificate of insurance showing active workers' comp coverage before any subcontractor starts work.
Q: Can I just have workers sign a contract saying they're independent contractors?
A written agreement alone does not determine status under Colorado law. The actual working relationship matters more than what the contract says. Factors like who controls the work, who supplies the tools, and how much direction is given all affect how the state classifies a worker. Misclassification carries serious penalties.
Workers' compensation is one of those coverage areas that seems simple until you dig into the specifics of your situation. Sole proprietor status, subcontractor relationships, seasonal help, construction versus non-construction work, all of it affects what you're required to carry and when.
If you're operating in Colorado Springs or anywhere on the Front Range and you're not completely sure your coverage is right, it's worth a quick conversation. Give us a call or start a quote online, and we'll sort out exactly where you stand.